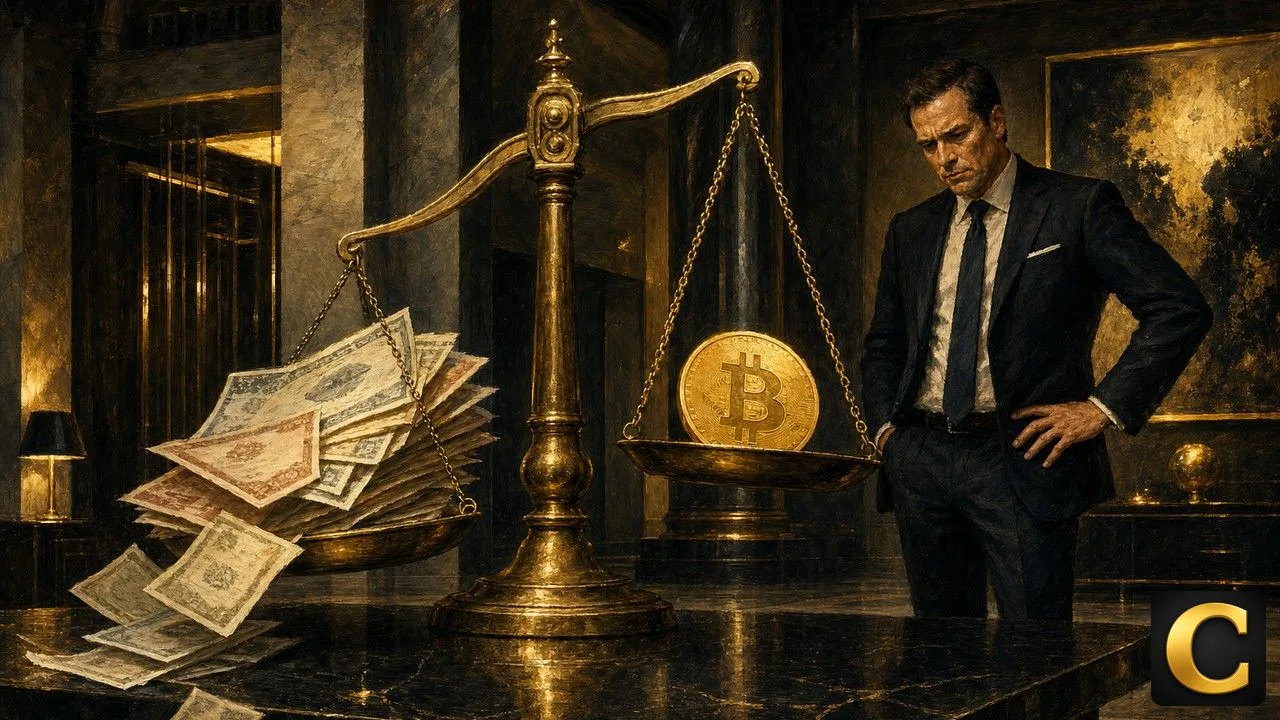
A bitcoin allocation funded out of the bond sleeve rather than the equity sleeve is the arbitrage Bitcoin Suisse put through its models this year, and the output is specific enough to argue with. A portfolio carrying no bitcoin returned 6.2% annualised in the test. At 1% the figure moved to 7.2%, and at 2.5% it reached 8.6%. The context behind the exercise matters as much as the output: hyperscaler capital expenditure is running above $800 billion this year, US federal debt has passed $40 trillion, and Treasury yields have returned to levels last seen during the global financial crisis. Two of the three legs of a conventional balanced book are therefore under pressure at the same time, which is what pushes an allocator to look at the third.
The Read
- Modelled returns rose from 6.2% with no bitcoin to 8.6% at a 2.5% weight.
- Allocations of 1%, 2.5%, 5% and 10% were all tested, funded from bonds.
- US federal debt above $40 trillion sits behind the weakening case for duration.
Get This Analysis Summarized by AI
ChatGPTBitcoin Suisse Runs the Numbers on an AI Heavy Book
The exercise comes out of the firm’s Crypto Wealth Management Report for 2026, and its framing is that investor attention stays trapped in AI until the speculative cycle breaks. That figure measures how concentrated the index has become. Equity books have drifted into a narrow group of technology names because that is where the earnings revisions have been.
Capital expenditure figures explain why the drift has been so hard to resist. Hyperscalers are expected to spend more than $800 billion in 2026, with projections above $1 trillion for 2027. Spending at that scale pulls suppliers, utilities and data centre operators into the same correlation cluster as the buyers themselves.
One thing to notice is how much of the demand is machine generated. The report flags that AI agents consume more than five times as many tokens as humans, which is the mechanism turning a software cycle into a hardware and energy cycle. That is also what makes the concentration structural rather than a sentiment phase.
Capital has been following that logic into private vehicles as well as listed ones. A $400M raise earmarked for AI and robotics is the kind of allocation that competes directly with a crypto sleeve for the same risk budget, which is the practical constraint behind the whole discussion.
That competition for the risk budget is what turns a bitcoin allocation from a thematic question into a funding question, and it is the reason the report tests the weights against the bond sleeve rather than against cash.
Where the 6.2% Baseline Goes When Bonds Fund the Trade
The mechanics are simple and that is the point. Four weights were tested, 1%, 2.5%, 5% and 10%, each funded by reducing the bond sleeve rather than the equity sleeve, with the full method set out in the wealth management report the firm publishes for asset managers. The firm’s conclusion across the full range was that BTC improved both absolute and risk adjusted returns.
Interest lies in the gradient between the first two steps. Going from nothing to 1% added a point of annualised return, moving 6.2% to 7.2%. Going from 1% to 2.5% added nearly a point and a half more, reaching 8.6%. A bitcoin allocation contributed more per unit of weight in the second step than in the first.
That pattern is a function of what was sold to pay for it. Duration has been the losing leg, with Treasury yields back at global financial crisis levels and federal debt above $40 trillion. Replacing an asset whose forward return has been marked down flatters any funding source.
Here is why the funding decision carries more weight than the sizing decision. Taking the weight out of bonds changes the risk profile of the whole book, well beyond the 2.5% that moved. A balanced portfolio holds duration for the drawdown it is supposed to cushion, and a bitcoin allocation does not perform that job on the same timeline.
Institutions that wanted duration exposure without the yield problem have been testing a middle path. A tokenized bond fund from New York Life moving onchain keeps the cash flow profile of fixed income while changing the settlement layer, which is a narrower change than swapping the asset class outright.
Also on CFinance:
- Rate Hike Expectations Reach 90% After Goldman Switches
- Trump Dividend Puts $1.2 Trillion on the Table
- Zcash ETF Tops $500M With $100M From a DCG Affiliate
The Case for Funding a Bitcoin Allocation From Duration
The bull case rests on the correlation argument rather than the return argument. If equity books are concentrated in one cluster and that cluster is driven by a single capital expenditure cycle, then adding more equity beta adds no diversification at all. The bond sleeve is the only place left to fund from.
Modelled outcomes hold steady across the tested range, which matters more than the headline number. A result that only worked at 10% would be a leverage story. A bitcoin allocation that improves risk adjusted returns from 1% upward is a diversification story, and a 1% weight is inside the mandate of most conservative books already.
Corporate treasuries reached this conclusion earlier and at far larger size. The debate there has moved past whether to hold the asset and on to capital allocation between the holding and the equity, which is where the argument over buyback priority against a $4.8B cash position sits today.
So the institutional version of this trade is a statement about portfolio construction. A bitcoin allocation here says that a 60/40 book built for a 2% inflation world with positive real yields does not exist any more, and that the replacement has to come from somewhere outside the two legs that are already correlated.
What Breaks If the Speculative Cycle Turns First
The bear case is inside the report’s own framing. If attention is trapped in AI until the speculative cycle breaks, then the break is the event that matters, and a bitcoin allocation is unlikely to be the hedge when it arrives. Crypto has tracked the same liquidity conditions as the technology complex through every drawdown of this cycle.
A second problem sits in the funding source. A book that sold duration to buy a 2.5% bitcoin allocation has removed the leg that historically cushioned an equity drawdown and replaced it with an asset that amplifies one. The modelled return improvement was measured over a period in which that specific scenario did not occur.
There is also a timing asymmetry an allocator has to price. Duration is cheap precisely because yields are back at crisis levels, so the asset being sold to fund the trade is the one with the most repriced forward return. Selling the cheap leg to buy the volatile one is a defensible trade at 1% and a different proposition at 10%.
The honest reading of the range is therefore that the low weights carry the argument and the high weights carry the risk. A 1% to 2.5% bitcoin allocation funded from bonds is a diversification decision with a modelled basis. Anything approaching the 10% test is a view on the AI cycle itself, dressed as an allocation.
More to come.
About the Author